

By Tonde Maruke
Zimbabwe’s Ministry of Mines recently made twin policy statements. The headline was the Strategic and Critical Minerals classification, with mandatory state shareholding. The other was a statement that small and medium-scale gold mining is now reserved exclusively for Zimbabweans.
Produce less than 20 kilograms of gold per month, or invest less than US$15 million, and you are small-scale. Foreign-controlled and small-scale means your titles are at risk by 1 January 2027.
For London-listed Kavango Resources, that is a direct hit.
In March this year, Kavango raised US$8.4 million. Last year, it heeded the government call to list on the VFEX, a listing presided over by the then Minister of Mines. It plans to build a 250-tonne-per-day plant at its Hillside Gold Project in Filabusi. At the planned 250 tonnes per day and Hillside’s reported grade of 0.86 grams per tonne, the operation would produce roughly 5-7 kilograms of gold per month. Total available capital sits at around US$13.5 million. On both production and investment, Kavango would be below the “small scale” threshold.
The real target?
The policy does not name any nationality. But government cited “unsustainable mechanised, non-standard mining practices by foreign investors” and community conflicts. In Zimbabwe’s small-scale gold sector, that maps well onto Chinese operators, who have dominated the space through tribute arrangements for over a decade, frequently fighting with local miners.
But the bigger question is about Zimbabwe’s ever-changing rules.
Zimbabwe has spent years courting foreign miners, including junior miners like Kavango. Ariana Resources, another foreign junior, is advancing a 1.4-million-ounce project at Dokwe. Such investments bet on policy stability.
Investors can handle indigenisation and state equity. These are now standard across Africa. What they cannot price in is uncertainty, a policy announced in May with a January deadline, or a mandatory government shareholding whose percentage and terms remain unspecified. For lenders underwriting any mine financing right now, that old Zimbabwe risk is keeps rising.
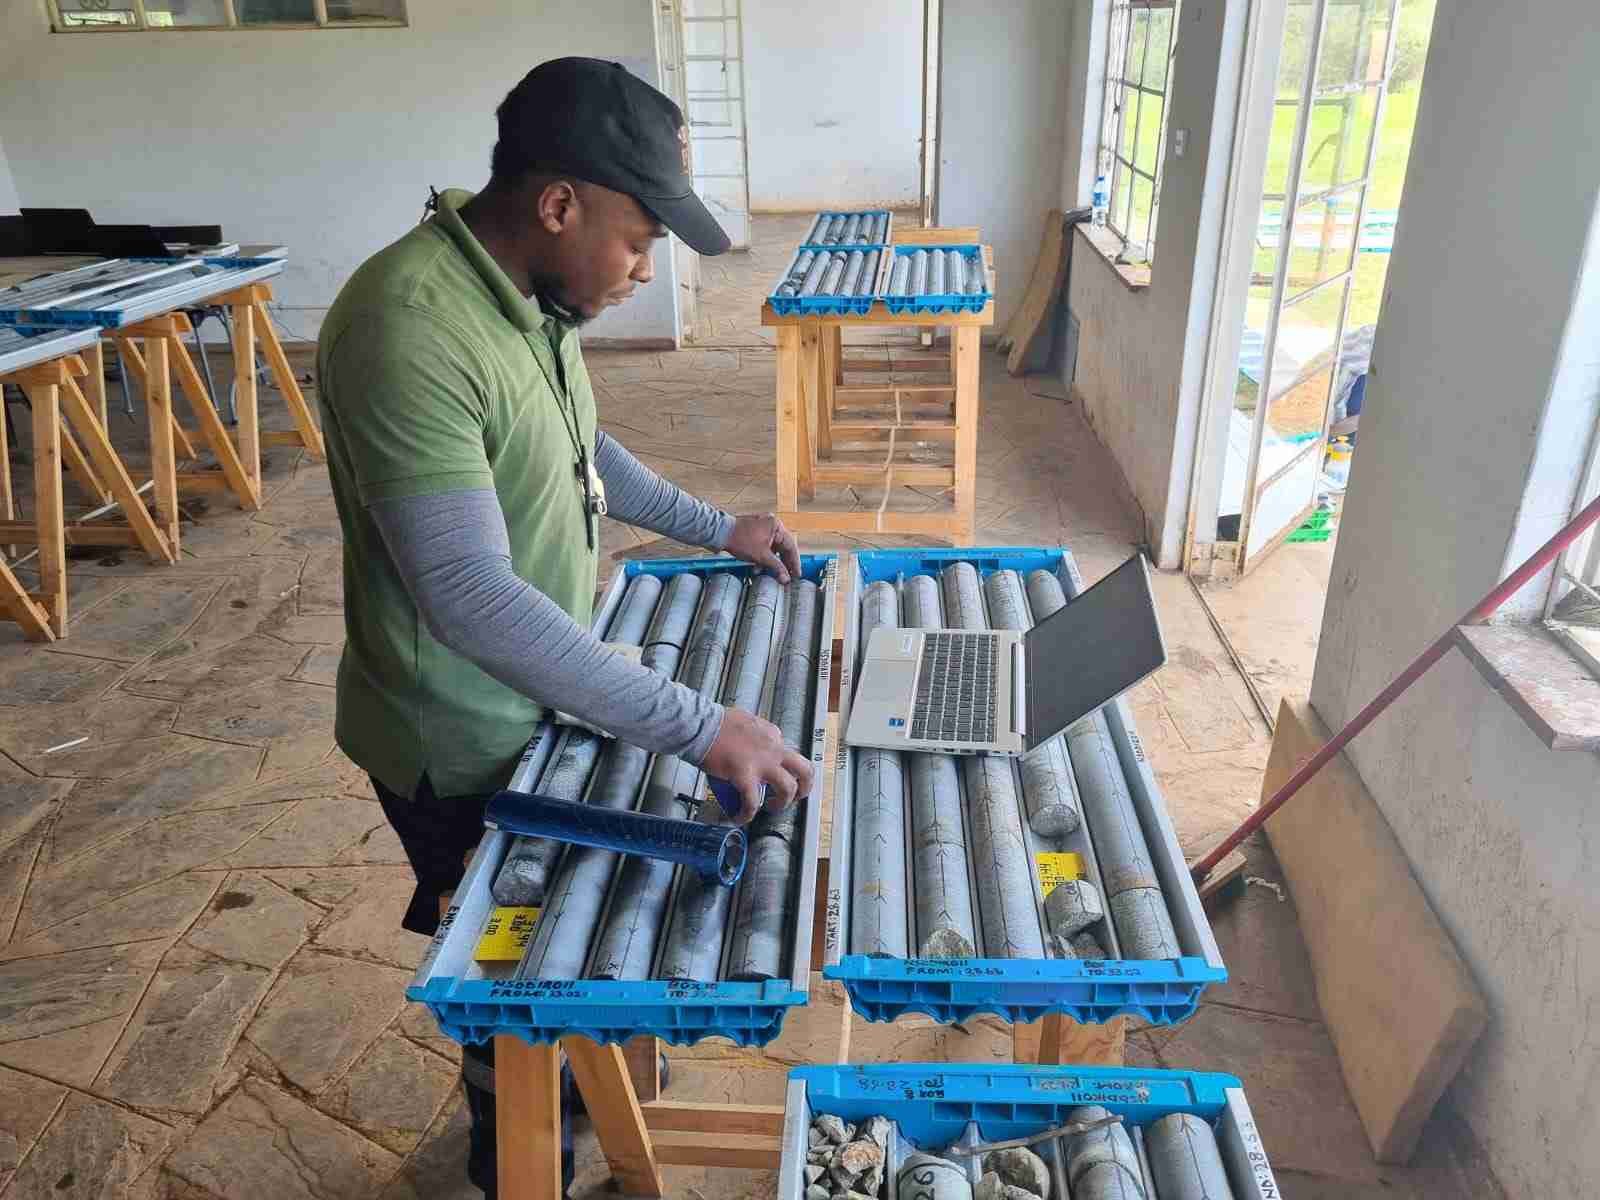
Zimbabwe produced 36.7 tonnes of gold in 2025. Getting to 50 tonnes requires new mines. New mines require exploration. Exploration is funded almost entirely by foreign junior capital, the same capital this policy puts at risk. A find too small for large-scale classification is now a liability for a foreign company. That changes the calculus for anyone considering early-stage risk in Zimbabwe.
“The country has made so much progress over the last 12 months and is starting to attract serious foreign investment,” says Ben Turney, former Kavango CEO, “Unfortunately, this move undoes a lot of that.”
Turney says for exploration, the $15 million capital threshold is “far too high for start-up exploration”. He adds that exploration funded by $2 million- $3 million leads to “substantial work and is far more in keeping with international standards.”
The government’s instinct to prioritise citizens in their own mineral sector makes sense. But the execution – seven months’ notice, undefined state equity terms, no clarity on exploration – is where Zimbabwe’s investment case again gets cloudy.
Listing on the VFEX in 2025, Kavango was full of praise for Zimbabwe, saying: “We believe that the more success we have, the greater the chance that other international firms will follow our lead to invest in this great country.”
The company is about to find out what the new rules actually mean. Others are watching closely.